
Class 2 “Regional” Railroads: Definition, List & Statistics
Last revised: August 9, 2026
By: Adam Burns
Between the six Class I freights and the hundreds of short lines sits a smaller but vital middle tier: the Class II regional railroad. Regionals are large enough to run multi-state or multi-hundred-mile line-haul service with modern motive power and welded-rail mains, yet small enough to stay close to industrial customers that Class I unit trains often bypass.
Ownership ranges from independents (such as Iowa Interstate and Reading & Northern) to holding-company properties (Watco’s Wisconsin & Southern, Genesee & Wyoming’s Buffalo & Pittsburgh and many others) and state-owned systems such as the Alaska Railroad. Roughly two dozen U.S. carriers typically sit in or near Class II status in any given year—the exact roster shifts with inflation thresholds, growth, and Class I acquisitions.
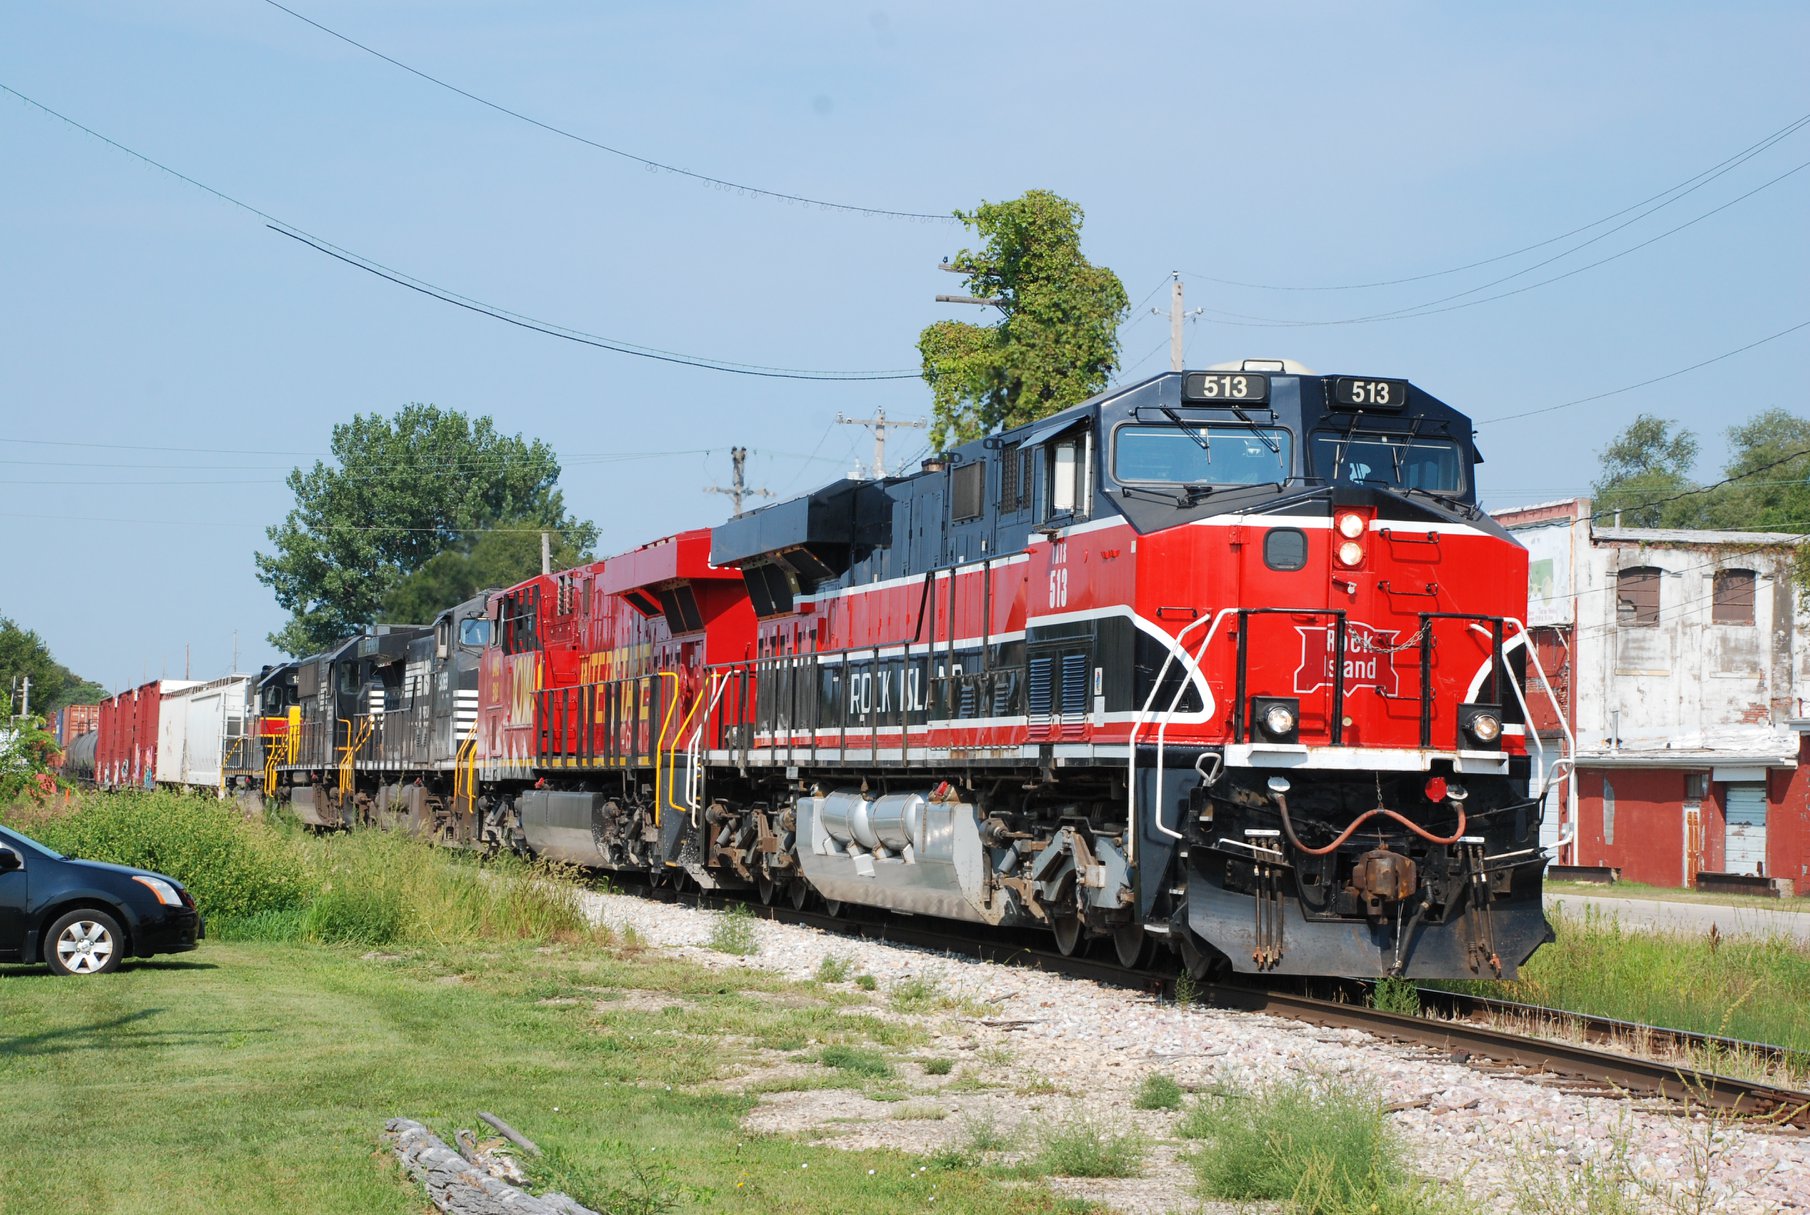
Iowa Interstate’s pair of Rock Island heritage units, ES44AC’s #513 and #516, lead eastbound freight CBBI through Silvis, Illinois on August 10, 2017. Doug Kroll photo.
Definition: STB Class II vs. AAR “Regional”
Two vocabularies often get mixed together. Keep them straight:
Surface Transportation Board (official revenue classes)
The STB classifies freights as Class I, II, or III by annual operating revenue, adjusted for inflation under 49 C.F.R. Part 1201. After the Board’s 2021 reset of the base year (from 1991 dollars to 2019 dollars), thresholds are higher than the old “$250 million / $20 million” ladder many printed sources still quote.
For 2025 (latest deflator factors published by the Board as of this revision):
- Class I: about $1.095 billion or more
- Class II: from about $49.1 million up to (but not including) the Class I floor
- Class III: below the Class II floor
Source: STB Economic Data — Revenue Deflators. Re-check EP 748 figures annually; they move with the railroad PPI deflator.
Older American-Rails and ASLRRA pages that still say Class II is “$39 million to $505 million (2016)” or similar are using a pre-reset scale. Treat 2025 STB numbers above as current for classification talk on this site.
Association of American Railroads / ASLRRA “regional” definition
Industry groups also use a practical size definition that does not always match pure STB revenue bands. ASLRRA summarizes a regional railroad as a line-haul carrier that is below the Class I revenue threshold and either:
- operates at least 350 route miles and earns at least about $20 million in revenue, or
- earns revenue between roughly $40 million and the Class I threshold regardless of mileage
That is why some well-known names are called “regionals” in trade talk even when a casual observer might call them large short lines—and why a few pure Class III switchers never get the regional label no matter how busy they are.
At a Glance
| Item | Detail (approximate; confirm sources) |
|---|---|
| STB Class II band (2025) | ~$49.1 million to ~$1.095 billion annual operating revenue |
| Typical U.S. Class II count | On the order of ~20 carriers (fluid) |
| Short line + regional combined (AAR/ASLRRA order of magnitude) | ~600+ freights; tens of thousands of route miles; first-/last-mile access for thousands of industries |
| Share of U.S. freight rail network | Class II + III often cited near 30% of mileage and ~10% of employees (AAR-style summaries) |
| Six Class I freights | BNSF, UP, CSX, NS, CN (U.S.), CPKC — see Class I overview |
The Federal Railroad Administration’s October 2014 capital-needs report (often still quoted for “21 regionals / 10,335 miles / $1.4 billion revenue”) is a useful historical snapshot, not a 2026 census. Prefer current AAR and ASLRRA fact sheets when you need a single public number.
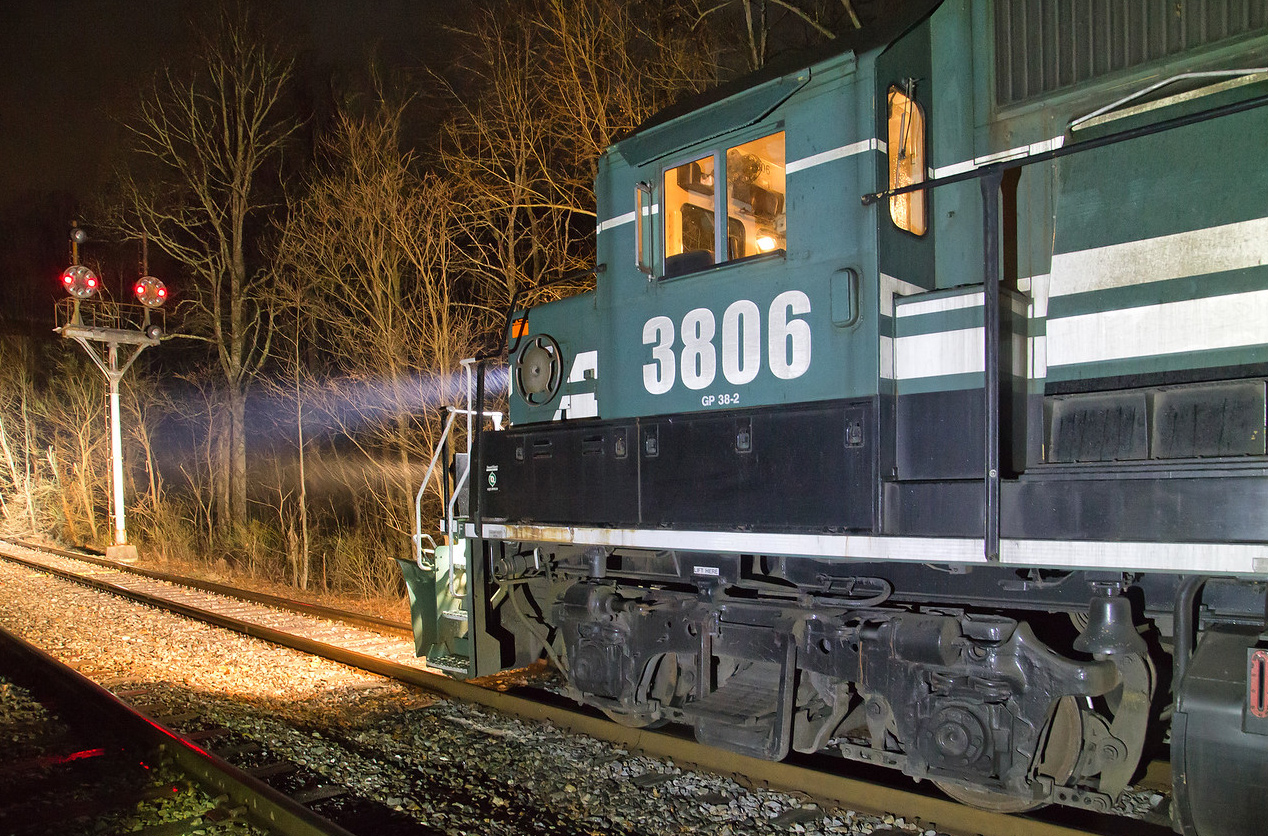
An Appalachian & Ohio GP38-2 and its string of empty coal hoppers await a clear signal along the historic Baltimore & Ohio’s “West End” at Berryburg, West Virginia. Loyd Lowry photo.
How Today’s Regionals Were Born
Most of the modern regional map is a product of the Staggers Rail Act of 1980. Deregulation made it far easier for Class Is to sell or spin off secondary mains and branches they no longer wanted to operate. Some sales were large enough to create Class II-scale systems from day one:
- Paducah & Louisville (1986) — former Illinois Central lines in western Kentucky
- Montana Rail Link (1987) — ex-Northern Pacific main across southern Montana (returned to BNSF operation January 1, 2024)
- Wheeling & Lake Erie (the modern W&LE) — rebuilt from former N&W / related properties in Ohio and Pennsylvania
- Wisconsin & Southern — revival of Milwaukee Road, Illinois Central, and C&NW branch country
- Reading & Northern — former PRR, Reading, LV, and CNJ secondary lines in eastern Pennsylvania
- Central Maine & Quebec (2014, from the Montreal, Maine & Atlantic / Bangor & Aroostook core) — sold to Canadian Pacific in 2020 and folded into the CP (now CPKC) system
Not every regional is a post-Staggers startup. Florida East Coast, New York, Susquehanna & Western, and (until its sale into CSX) historic New England systems under the Pan Am banner had roots stretching back a century or more.
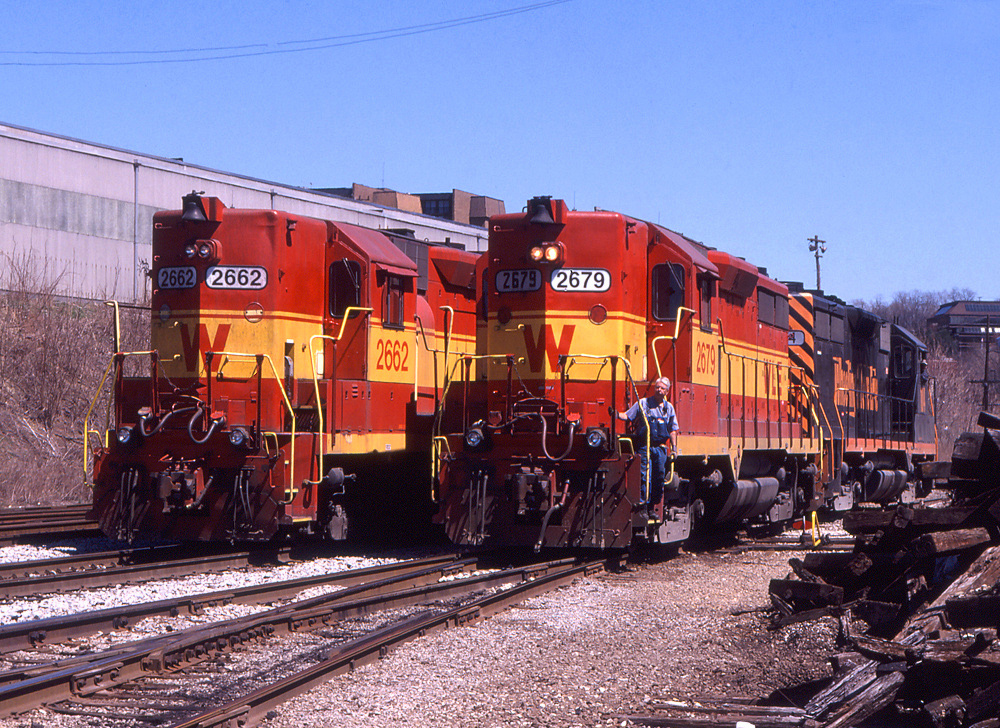
Two Wheeling & Lake Erie GP35s, #2662 and #2679 sporting the red and orange livery, are busy at Rook Yard in Green Tree, Pennsylvania on April 9, 2005. Wade Massie photo.
Regional “Fallen Flags” and Class I Appetite
Successful regionals often become acquisition targets. Notable examples:
- Wisconsin Central (reborn 1987 on Milwaukee Road / Soo castoffs; later Green Bay & Western, Fox River Valley, Algoma Central) — purchased by Canadian National in 2001 after a decade of strong growth that flirted with Class I scale
- Gateway Western (ex-Chicago & Alton / CM&W territory) — later into Kansas City Southern
- Elgin, Joliet & Eastern; Dakota, Minnesota & Eastern; Iowa, Chicago & Eastern — absorbed into Canadian systems (CN / CP) in the 2000s–2010s era of midwestern expansion
- Pan Am Railways — CSX completed acquisition June 1, 2022, expanding CSX deep into New England
- Montana Rail Link — BNSF resumed operation of the former MRL leased main January 1, 2024 (MRL as an independent operator ended)
The pattern is consistent: regionals prove a corridor, invest, and either remain independent niche champions or get reabsorbed when a Class I needs capacity, connectivity, or competitive position.
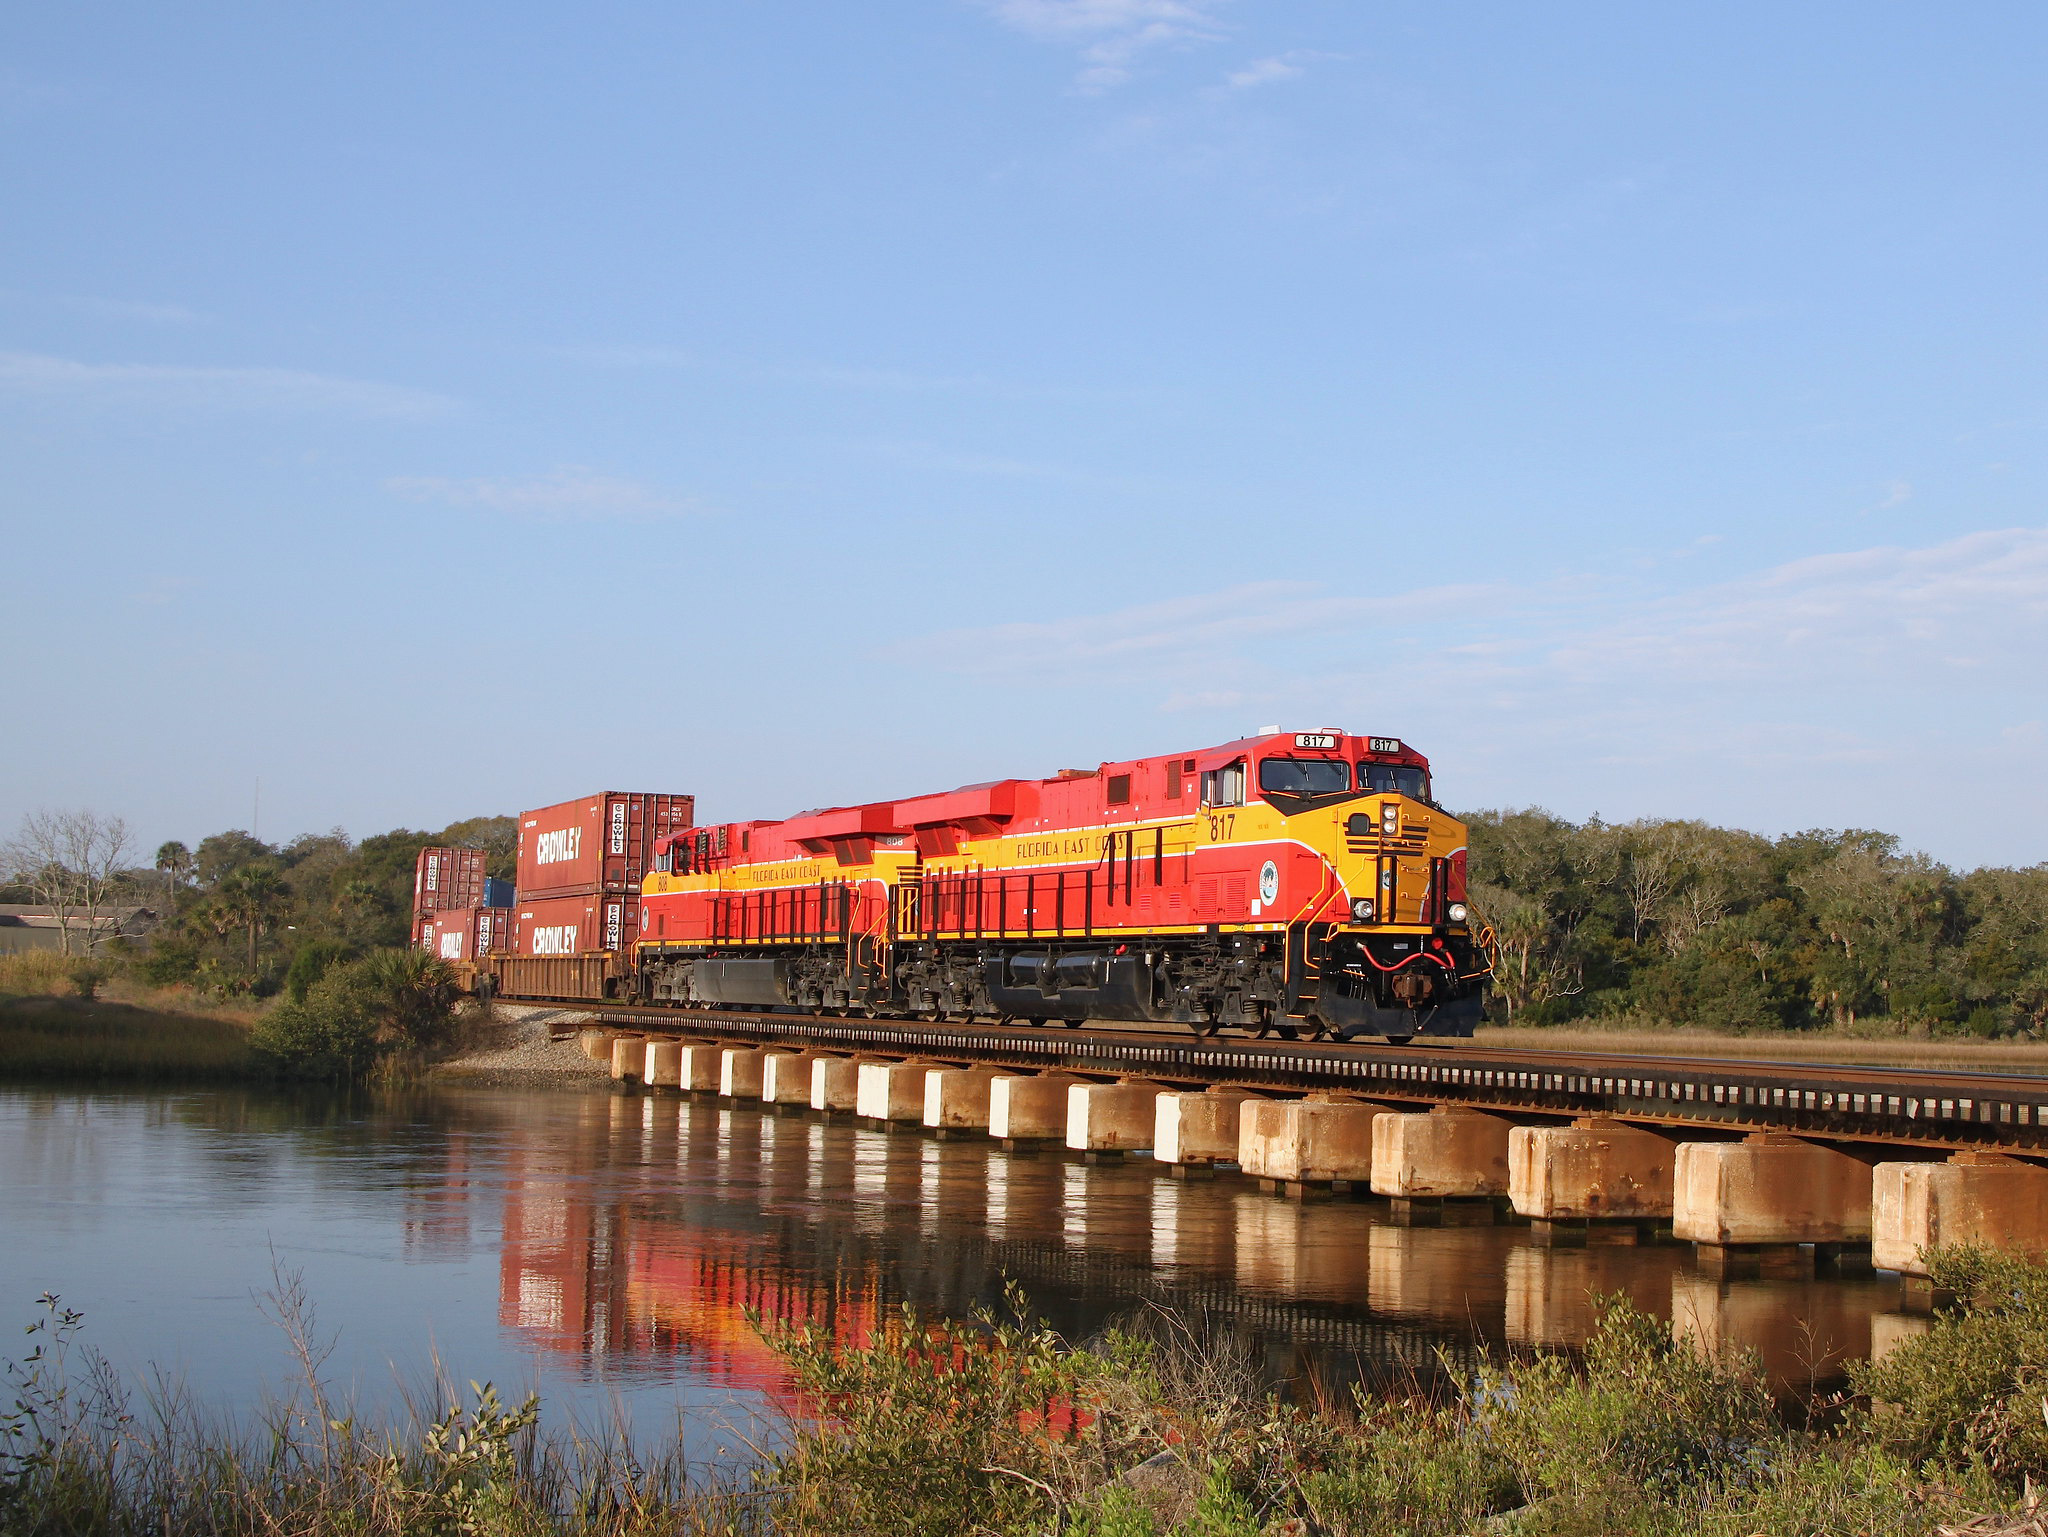
A pair of Florida East Coast ES44C4’s lead containers near St. Augustine, Florida on February 15, 2015. Warren Calloway photo.
What Regionals Look Like Today
Modern Class IIs often run new or nearly new six-axle road power, distributed power on heavy trains, and PTC where required—traits that make them easy to mistake for Class Is trackside. Holding companies such as Genesee & Wyoming and Watco have standardized paint schemes across many properties, while independents such as Iowa Interstate and Reading & Northern keep distinctive liveries and heritage programs that railfans still chase.
Traffic is a mix of local industrial switching and longer regional hauls: coal and coke where geology still supports it, aggregates, chemicals, paper and forest products, grain, automotive, and growing intermodal on corridors like FEC’s Florida main. Customer intimacy remains the regional advantage over pure Class I operating plans.
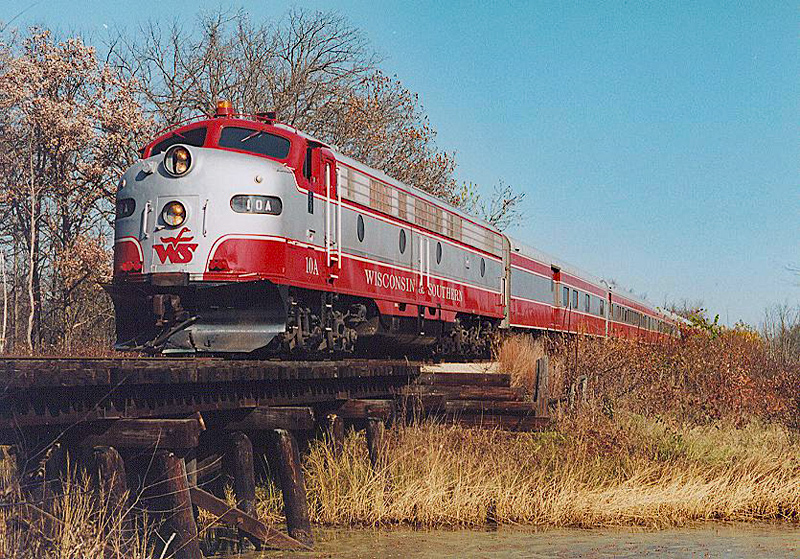
Wisconsin & Southern E9A #10-A leads a public excursion westbound near Woodman, Wisconsin on October 21, 2000. Doug Kroll photo.
Company Profiles on American-Rails.com
Featured Class II / large regional systems (status noted where recently changed):
- Buffalo & Pittsburgh (G&W)
- Central Oregon & Pacific
- Florida East Coast
- Indiana Rail Road
- Iowa Interstate
- Montana Rail Link (independent operations ended; BNSF MRL Subdivision from Jan. 1, 2024 — historical profile)
- New York, Susquehanna & Western
- Paducah & Louisville
- Pan Am Railways (into CSX June 1, 2022 — historical profile)
- Providence & Worcester (G&W)
- Reading & Northern
- Wheeling & Lake Erie
- Wisconsin & Southern
Canadian regional interest
Defunct / absorbed regionals (selected profiles)
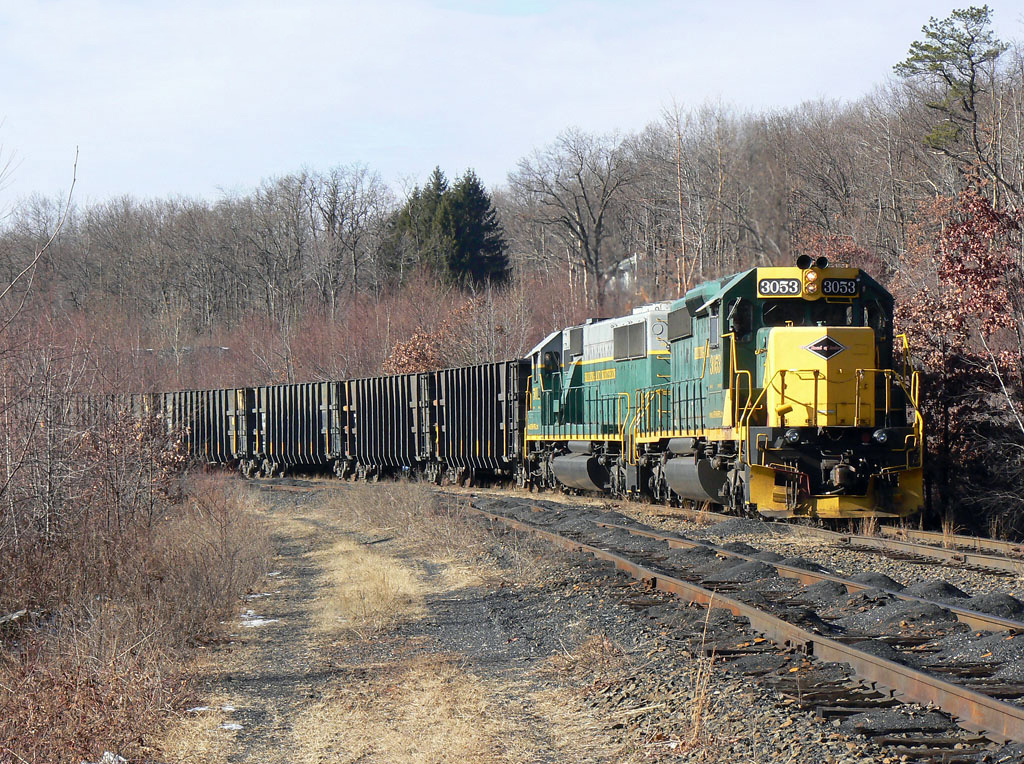
Reading & Northern SD40-2 #3053 leads the “Jeddo Job” as it waits to be loaded with culm at Jeddo Highland Coal Company’s facility near Ebervale, Pennsylvania on December 22, 2010. Mike Thomas photo.
Why Regionals Still Matter
Post-1980 short line and regional success preserved thousands of miles that would otherwise have been abandoned. That has forced a reassessment of the 1970s–1980s cull of secondary mains: corridors that looked surplus under heavy regulation look strategic under modern intermodal and industrial-development economics. Gregory Schneider’s Rock Island Requiem and similar histories make the case that excessive regulation, not a lack of traffic potential, created much of the crisis that produced today’s regional map.
For railfans, regionals remain the middle ground between look-alike Class I unit trains and pure local switch jobs: distinctive paint (where it survives), manageable geography, and freights that still feel regional rather than continental.
Learn more from the trade association that represents this segment: American Short Line and Regional Railroad Association (ASLRRA).
Related Reading on American-Rails.com
- Class I Railroads: Revenue, Statistics & Overview
- Short Line Railroads (Class III)
- Canadian Pacific Kansas City (CPKC)
- American Railroad History
- Fallen Flags
Revenue thresholds and ownership change. Confirm STB classification figures and carrier status on official sources before relying on any single year’s list. Information compiled August 9, 2026.
Recent Articles


-
Canadian National Railway: Map, Logo, History, Photos
Sep 16, 26 12:27 AM
 Canadian National—name Dec 20 1918, incorporated June 6 1919, Grand Trunk Jan 20 1923. Crown corporation, IPO Nov 17 1995. IC, Wisconsin Central, BC Rail, EJ&E. Class I, mark CN.
-
Buffalo, Rochester and Pittsburgh Railway: "Safety and Service"
Sep 16, 26 12:12 AM
 Buffalo, Rochester & Pittsburgh—Rochester & State Line 1869, BR&P March 12 1887. Pennsylvania coal to Buffalo and Rochester. B&O January 1 1932. All-time steam roster, LL 2-6-6-2s, XX…
-
Buffalo Creek & Gauley Railroad: Map, Roster, Logo, Photos
Sep 15, 26 11:55 PM
 Buffalo Creek & Gauley—Elk River Coal & Lumber, April 1 1904, Dundon–Widen. Last all-steam WV coal road, February 27 1965. All-time steam roster, #4 Baldwin 59472, Majestic and Elk River diesels…
-
Buffalo and Susquehanna Railroad: Map & History
Sep 15, 26 11:42 PM
 Buffalo & Susquehanna—Goodyear hemlock railroad, Sinnemahoning Valley December 14 1885, 1893 merger, coal to Sagamore, Buffalo extension, bankruptcy May 6 1910, B&O 1932, WAG 1956.
-
WMSR Allegheny Mountain Dinner Train (2026): Dates & Tickets
Sep 15, 26 11:36 PM
 2026 Western Maryland Scenic Allegheny Mountain Dinner Train—Cumberland, 3 hours, 21+, Saturday 7 p.m. Confirm on wmsr.com.
-
Boston and Albany Railroad: Map & History
Sep 15, 26 11:28 PM
 Boston & Albany Railroad—Boston & Worcester June 23 1831, Western Railroad across the Berkshires, merger 1867–70. NYC 99-year lease July 1 1900. Berkshires, New England States, CSX and MBTA today.
-
Grand Bellevue Dinner Train (2026): Portsmouth, Rhode Island
Sep 15, 26 11:14 PM
 2026 Grand Bellevue Rail Dining in Portsmouth, RI—2.5-hour seated dinner on Narragansett Bay. Fall/winter TBA after Aug. 29. Confirm on thegrandbell.com.
-
The "John Bull": The C&A's First Locomotive (1831)
Sep 15, 26 11:01 PM
 John Bull locomotive—Stephenson Planet-type 0-4-0, 1831. Dripps assembly, 4-2-0 rebuild, cowcatcher. Specs, Camden & Amboy career, Smithsonian 1884, 1981 steam-up, 1939 replica.
-
Napa Valley Wine Train Dining (2026): Lunch, Dinner & Vista Dome
Sep 15, 26 10:56 PM
 2026 Napa Valley Wine Train dining—downtown Napa, 36-mile round trip, gourmet lunch and dinner, Vista Dome. Confirm packages on winetrain.com.
-
My Old Kentucky Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 10:50 PM
 2026 My Old Kentucky Dinner Train in Bardstown—2.5 hours, 35-mile round trip, four-course dinner from $116. Confirm on kydinnertrain.com.
-
LaSalle Street Station: One Of Chicago's Great Terminals
Sep 15, 26 10:42 PM
 LaSalle Street Station—Rock Island October 10, 1852. Frost & Granger July 1, 1903. 20th Century Limited, Rockets, Golden State. Headhouse razed 1981. Metra Rock Island District today.
-
Charlie Russell Chew Choo (2026): Montana Dinner Train from Lewistown
Sep 15, 26 10:39 PM
 2026 Charlie Russell Chew Choo dinner train—Hanover/Lewistown, 4.5 hours, 56-mile round trip, prime rib. Adult $151. Remaining listed dates sold out. Confirm on montanadinnertrain.com.
-
Central Pacific Railroad: Map, History, Facts, Logo
Sep 15, 26 10:30 PM
 Central Pacific—Judah, Big Four, June 28 1861. Sierra, Chinese labor, Donner Summit Tunnel. Ten-mile day April 28 1869. Promontory May 10. Southern Pacific lease April 1 1885. Dissolved June 30 1959…
-
Bessemer & Lake Erie Railroad: "The Bessemer Road"
Sep 15, 26 05:20 PM
 Bessemer & Lake Erie—Bear Creek 1865, Carnegie 1897, U.S. Steel 1901. Ore south from Conneaut, coal north. 2-10-4s, Missabe sister road. CN May 10, 2004. Complete corporate history.
-
Bangor and Aroostook Railroad: "Serving Northern Maine"
Sep 15, 26 05:05 PM
 Bangor & Aroostook—chartered February 13, 1891, first trains January 1, 1894. Potatoes, paper, Searsport, State of Maine reefers. MM&A 2003, Lac-Mégantic 2013, CP 2020, CPKC today. Complete co…
-
Baltimore & Ohio Chicago Terminal Railroad: Map and History
Sep 15, 26 03:11 PM
 B&OCT—formed January 6, 1910 to buy Chicago Terminal Transfer. Grand Central, Barr Yard, 78 route-miles. Assigned B&O steam. Complete diesel roster. CSX paper subsidiary, mark BOCT.
-
The "Alphabet Route" (Railroad): Photos and History
Sep 15, 26 02:53 PM
 Alphabet Route—eight railroads, not one company. P&WV to Connellsville February 11, 1931. Alpha Jets Chicago/St. Louis–New York/Boston. NKP, W&LE, P&WV, WM, Reading, CNJ, L&HR, New Hav…
-
Milwaukee Road Livestock Operations: Cattle, Dakotas & Montana
Sep 15, 26 02:36 PM
 Milwaukee Road livestock traffic—Dakota and Montana cattle, Iowa hogs, Chicago markets, 28-hour law, head-end stock cars. By 1974 mostly Montana. Rick Burn’s Helena speech. Operations history, not the…
-
Spirit of Jasper Ride & Dine (2026): Season Pause
Sep 15, 26 02:29 PM
 Spirit of Jasper Ride & Dine in Jasper, Indiana—seated meal on board. Operator: not running public trains for 2026. Depot remains open as a rental. Confirm on spiritofjaspertrain.com.
-
South Carolina Canal & Rail Road Company: Map and History
Sep 15, 26 01:59 PM
 South Carolina Canal & Rail Road—chartered December 19, 1827. Best Friend of Charleston, 136 miles Charleston–Hamburg October 1833, Aiken inclined plane. South Carolina Railroad 1844, Southern 189…
-
The Practice of Double-Heading: The Steam Era
Sep 15, 26 01:43 PM
 Doubleheading—two locomotives on the point, each with its own steam crew. Not a rear helper, not diesel MU. How it worked, PRR 1877, mountain grades, and what MU ended.
-
Mohawk and Hudson Railroad: Map, Pictures, Locomotives
Sep 15, 26 01:20 PM
 Mohawk & Hudson Railroad—New York’s first railroad, chartered April 17, 1826. DeWitt Clinton, inclined planes, Albany & Schenectady 1847, first New York Central May 17, 1853. Complete corporat…
-
Essex Clipper Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 01:09 PM
 2026 Essex Clipper Dinner Train in Essex, CT—2.5 hours, four-course meal $129.99, 18+. Fall dates through Oct. 25. Confirm on essexsteamtrain.com.
-
Camden & Amboy Railroad: Map, History, Photos
Sep 15, 26 12:53 PM
 Camden & Amboy Railroad—chartered February 4, 1830. Joint Companies monopoly with the Delaware & Raritan Canal, John Bull, T-rail. United New Jersey 1872, PRR 999-year lease 1871. Complete corpora…
-
Cafe Lafayette Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 12:47 PM
2026 Cafe Lafayette Dinner Train in North Woodstock, NH—2 hours, 20 miles, five-course meal from $125. May–October. Confirm on nhdinnertrain.com. -
Christmas Train Ride Locations (2026): A Complete Guide
Sep 15, 26 10:47 AM
 2026 Christmas train rides by state—Santa, North Pole Express, and holiday trains. Not Polar Express. State guides and product pages. Confirm dates on each railroad.
-
Baltimore & Ohio Railroad: Linking 13 Great States With The Nation
Sep 15, 26 10:22 AM
 Baltimore & Ohio Railroad—first U.S. common carrier, chartered February 28, 1827. Wheeling 1853, Chicago 1874, C&O control 1963, Chessie 1973, into CSX April 30, 1987. Complete corporate history.
-
Delaware & Hudson Railway: The Bridge Line
Sep 15, 26 09:59 AM
 Delaware & Hudson Railway—Wurts brothers canal 1823, gravity railroad 1829, Stourbridge Lion, Bridge Line to Montreal. Guilford 1984, CP 1991, NS south line 2015, CPKC north.
-
Delaware & Hudson Diesel Roster (All-Time)
Sep 15, 26 12:17 AM
 All-time Delaware & Hudson diesel roster—Alco S-2s through C-628s and PA-4s, GE U-boats, Baldwin RF-16s, EMD SD45s and GP38-2/GP39-2s. Serials, dates, dispositions.
-
Granite Railway, Our Country's First Railroad
Sep 14, 26 11:28 PM
 Granite Railway of Quincy, Massachusetts—chartered March 4, 1826, opened October 7, 1826. Gridley Bryant, 5-foot gauge, horses, Bunker Hill Monument stone. First commercial U.S. railroad.
-
Milwaukee Road Skytop Lounges: History, Specs & Floor Plans
Sep 14, 26 11:09 PM
 Milwaukee Road Skytop observation cars—Brooks Stevens, 1948. Four Rapids parlor-lounges from Milwaukee Shops, six Creek sleeper-lounges from Pullman-Standard. Floor plans, roster, preservation.
-
West Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 11:02 PM
2026 West Virginia Christmas trains—Potomac Eagle North Pole Express in Romney and Christmas at Cass. Not Polar Express. Elkins Polar is not listed for 2026. -
Railroads Of Today: Class I Map, PSR & the 2026 Industry
Sep 14, 26 10:30 PM
 U.S. freight rail in 2026—six Class I railroads on a nearly 140,000-mile network. PSR as everyday practice, how the STB works, traffic mix, short lines and regionals.
-
Railroad History (USA): Timeline, Facts & How the Network Was Built
Sep 14, 26 10:03 PM
 Full U.S. railroad history hub—origins and inventors, Golden Age peak mileage, Civil War and transcontinental, streamliners, ICC regulation, Penn Central and Conrail, Staggers Act, PSR, and today’s Cl…
-
Railroads In The 2020s: CPKC, East Palestine & the UP–NS Case
Sep 14, 26 09:51 PM
 U.S. railroads 2020–2026—Class I mileage 91,773 in 2020. COVID traffic drop, CPKC April 14 2023, East Palestine Feb. 3 2023, UP–NS $85 billion case still before the STB.
-
Railroads In The 2010s: PSR, Coal’s Decline & Positive Train Control
Sep 14, 26 03:51 PM
 U.S. railroads 2010–2020—Class I mileage 95,573 to 91,773. Buffett closed BNSF Feb. 12 2010, Harrison at CP June 29 2012 and CSX 2017, PTC deadline Dec. 31 2018.
-
Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 03:46 PM
 2026 Virginia Christmas trains—Virginia Scenic Railway Santa Express from Staunton, about 60 minutes. Confirm dates. Not Polar Express.
-
MARC Train: Maryland Commuter Rail History, Lines & Roster
Sep 14, 26 01:16 PM
 MARC Train history—Maryland Rail Commuter 1984, B&O and PRR corridors, Penn/Camden/Brunswick lines, Silver Spring 1996, all-time locomotive roster.
-
Railroads In The 2000s: Merger Freeze, Wisconsin Central & Buffett
Sep 13, 26 07:57 AM
 U.S. railroads 2000–2010—Class I mileage 99,250 to 95,573. STB merger freeze March 17 2000, CN–WC Oct. 9 2001, BNSF Railway Jan. 24 2005, Buffett Nov. 3 2009.
-
Railroads In The 1990s: Mega-Mergers, Conrail’s Split & the STB
Sep 13, 26 12:13 AM
 U.S. railroads 1990–2000—Class I mileage 119,758 to 99,250. BNSF Sept. 22 1995, UP–SP Sept. 11 1996, Conrail split June 1 1999, ICC Termination Dec. 29 1995.
-
Railroads In The 1980s: Staggers, Mega-Mergers & Conrail’s IPO
Sep 12, 26 11:12 PM
 U.S. railroads 1980–1990—Class I mileage 164,822 to 119,758. Staggers Oct. 14 1980, CSX and Norfolk Southern, UP–Missouri Pacific–Western Pacific, Conrail IPO March 26 1987.
-
Wabash Class O-1 4-8-4s: History, Roster & Specifications
Sep 12, 26 11:01 PM
 Wabash Class O-1 4-8-4s—Baldwin 1930–31, twenty-five engines 2900–2924. Fast freight, complete roster, specifications. None preserved.
-
Staggers Rail Act of 1980: Statute, Contract Rates & the ICC
Sep 10, 26 11:23 PM
 Staggers Rail Act, Pub. L. 96-448, signed October 14, 1980. Harley Staggers, S.1946, contract rates, 180% variable-cost test, abandonments, short lines.
-
Rock Island E8A 652: Bicentennial Independence Paint & History
Sep 10, 26 10:42 PM
 Rock Island E8A 652—EMD March 1952, serial 15199. 20th Century Railroad Club Independence bicentennial scheme, Peoria and Quad Cities Rockets, Midland Railway, Manly Junction Museum.
-
Vermont Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 10:37 PM
2026 Vermont Christmas trains—Okemo Valley Holiday Express from Chester Depot Dec. 19–20. Polar is Burlington Dec. 5–6 only. -
Railroads In The 1970s: Penn Central, Amtrak & Conrail
Sep 10, 26 10:18 AM
 U.S. railroads 1970–1980—196,479 miles at the decade’s start. Penn Central bankruptcy June 21 1970, Amtrak May 1 1971, 3R/4R Acts, Conrail April 1 1976, Rock Island 1975, Milwaukee 1977.
-
Railroads In The 1960s: Mergers, Passenger Collapse & Penn Central
Sep 10, 26 10:03 AM
U.S. railroads 1960–1970—207,334 to 196,479 miles. Erie Lackawanna 1960, C&O–B&O 1963, N&W–Nickel Plate 1964, SCL 1967, Penn Central Feb. 1 1968. -
South Carolina Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:36 AM
 2026 South Carolina Christmas trains—South Carolina Railroad Museum Santa Train in Winnsboro. Confirm December dates. Not Polar Express. Drop light-festival padding.
-
Steam Locomotive Feedwater Heaters: Elesco, Coffin & Worthington
Sep 10, 26 08:29 AM
 Steam locomotive feedwater heaters—open Worthington vs closed Elesco and Coffin. How they work, how to identify them on a smokebox, and why not every engine had one.
-
Oregon Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:22 AM
2026 Oregon Christmas trains—Portland Holiday Express, Garibaldi Candy Cane Express, Sumpter Valley Christmas Trains Dec. 11–13. Polar is Mount Hood.


